
The rapid shift toward online pet retail—driven by giants like Chewy, Amazon, and direct-to-consumer (D2C) brands—is reshaping the traditional veterinary business model. Historically, brick-and-mortar clinics relied heavily on product sales (pharmaceuticals, parasiticides, therapeutic diets, and supplements) to subsidize their clinical medical services.
Online platforms have directly disrupted these core high-margin profit centers, forcing clinics to fundamentally change how they generate revenue and structure their operations.
1. Where Revenue Is Being Lost
-
Pharmacy Profit Erosion: In-house dispensaries once generated up to 20–30% of a practice’s gross revenue with high margins (often 100%+ markups on flea/tick, heartworm, and chronic meds). Online fulfillment and Auto-ship subscriptions have heavily eroded repeat prescription sales.
-
Therapeutic Diets & Specialty Products: Heavy, bulky specialty diets (Hill’s, Royal Canin, Purina Pro Plan) were traditionally carried home from the clinic. E-commerce home-delivery has captured the majority of this recurring retail market.
-
Administrative Friction: Clinics now spend significant unpaid staff hours reviewing, verifying, and processing third-party digital prescription requests coming from external online retailers.
2. How Practices Are Rebalancing & Pivoting
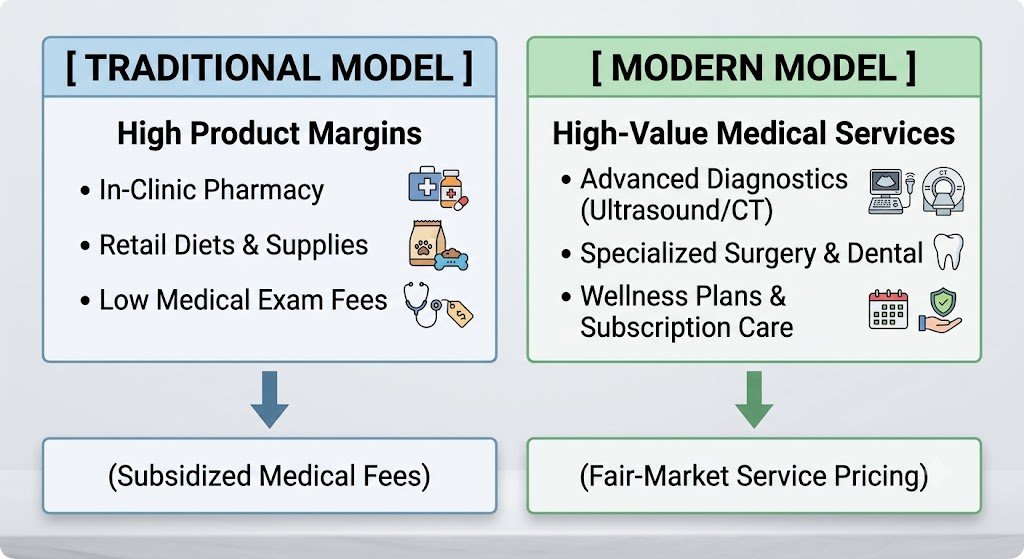
To offset lost product margins, veterinary practices have transitioned from a product-subsidized business model to a services-led economic model:
-
Re-Pricing Professional Services: Clinics have raised prices on exams, diagnostic panels, imaging, surgeries, and dental prophylaxis to accurately reflect true medical overhead rather than relying on pharmacy profits.
-
Adopting White-Labeled Online Stores: Practices partner with platforms like Vets First Choice / Covetrus or VetSource to launch their own branded e-commerce storefronts. This lets clients order prescribed items directly through the clinic’s system for home delivery, recovering recurring revenue with zero physical inventory costs.
-
Wellness Subscriptions: Many practices are bundling annual care (vaccines, bloodwork, dental cleanings, virtual check-ins) into auto-billed monthly membership plans, securing recurring service revenue.
-
Shifting Focus to Non-Commoditizable Care: Clinics are expanding offerings that cannot be ordered online: complex dentistry, urgent care, specialized surgery, physical therapy, and acute diagnostics.
3. Threat: Digital Players Entering Clinical Services
The competitive pressure is evolving beyond simple product retail. Major online retailers are acquiring or building physical clinical infrastructure:
-
Chewy’s Physical Footprint: In addition to launching Chewy Vet Care brick-and-mortar clinics, Chewy’s landmark acquisition of corporate practice group Modern Animal created a seamlessly integrated ecosystem connecting online retail, home pharmacy, and physical clinical care under one umbrella.
-
Telehealth Triage: Digital platforms offer on-demand virtual vet consultations. While these often direct clients to local clinics for hands-on care, they divert initial triage and minor consultations away from traditional practices.

