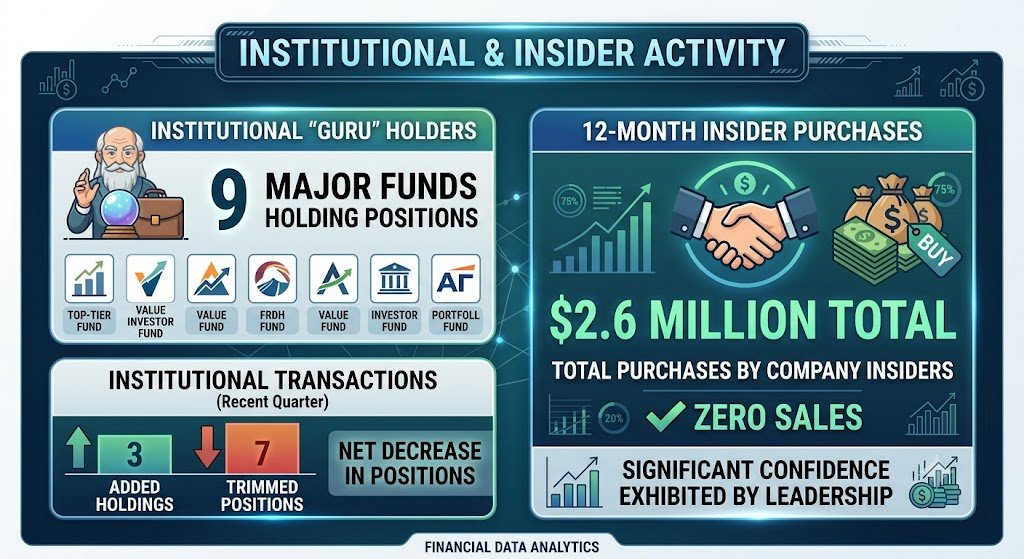

GREENFIELD, IND. — Shares of Elanco Animal Health Inc. (NYSE: ELAN) rose 4.4% to reach $23.55 this week, trading comfortably within its 52-week range of $19.40 to $27.98. The recent upward price action reflects strong technical momentum and significant executive confidence, highlighted by $2.6 million in insider share purchases over the past 12 months with zero recorded insider sales.
However, fundamental valuation metrics present a complex picture for animal health investors. According to some reported estimates, ELAN’s intrinsic value stands at $16.70 per share, placing the current market price at a 41.0% premium (overvalued).
Persistent profitability challenges and net cash flow losses continue to weigh on earnings-based multiples, creating a noticeable divergence between internal leadership optimism and traditional fundamental valuation models.
Valuation Dynamics: Revenue Multiples vs. Intrinsic Value
Because Elanco has faced ongoing net profitability constraints, standard Trailing Twelve Month (TTM) Price-to-Earnings (P/E) ratios are currently unavailable. Market analysts are primarily relying on Price-to-Sales (P/S) multiples and forward-looking estimates to evaluate the firm’s capital structure.
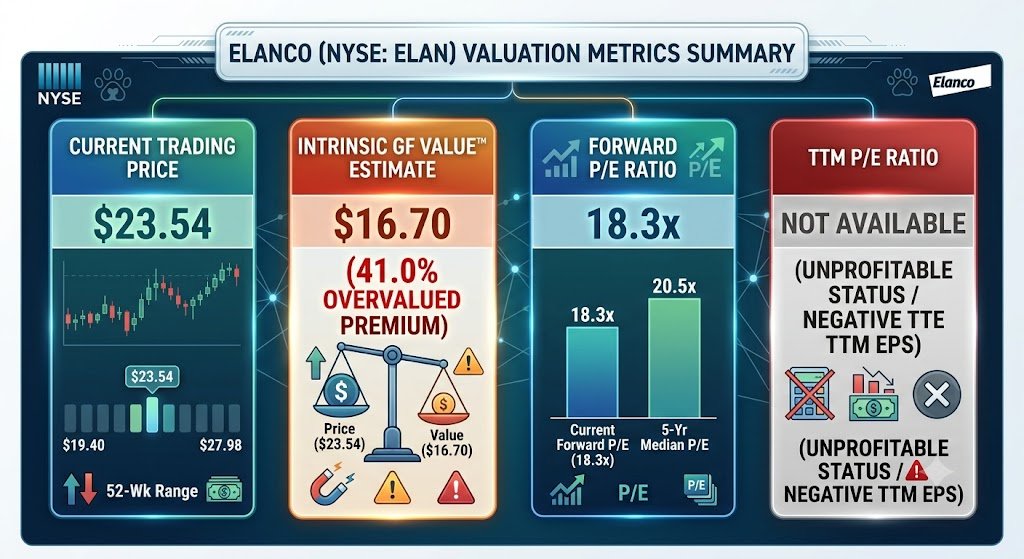
While ELAN appears overvalued against its $16.70 intrinsic baseline, its forward P/E of 18.3x trades below its historical 5-year median P/E of 20.5x. This discount suggests that forward-looking market projections are pricing in operational recovery as new companion animal dermatology and parasiticide assets scale commercially.
-
Institutional Realignment: Institutional activity remains cautious, with seven major funds reducing their positions while three expanded their stakes in recent quarters.
-
Bullish Executive Conviction: Conversely, corporate insiders have bought $2.6 million worth of ELAN stock over the past 12 months without selling a single share. This aggressive insider accumulation signals strong internal confidence in Elanco’s long-term commercial pipeline and debt-deleveraging roadmap.