
Swedencare AB reported higher revenue for the third quarter of 2026, but the Swedish pet-health group’s latest results reveal a marked slowdown in underlying growth and lower operating earnings. Revenue reached SEK 732.2 million, up 3% year on year, while organic, currency-adjusted growth fell to 2% from 15% in the corresponding quarter of 2025. Operational EBITDA declined 3% to SEK 150.1 million, and the company said full-year double-digit organic growth was no longer a probable outcome.
The interim report, published on 21 October 2026, points to a business with contrasting regional and operational performance: Europe and the Production segment continued to grow strongly, while North America remained challenging. Production disruption, supply-chain delays and weaker-than-expected sales from European veterinary brands late in the quarter contributed to the shortfall.
Key financial results: Q3 2026
Financial metric |
Q3 2026 |
Q3 2025 |
Year-on-year change |
|---|---|---|---|
Net revenue |
SEK 732.2m |
SEK 712.9m |
+3% |
Organic, currency-adjusted growth |
2% |
15% |
−13 percentage points |
Operational EBITDA |
SEK 150.1m |
SEK 154.9m |
−3% |
Operational EBITDA margin |
20.5% |
21.7% |
−1.2 percentage points |
Operational EBIT |
SEK 122.3m |
SEK 132.5m |
−8% |
Operational EBIT margin |
16.7% |
18.6% |
−1.9 percentage points |
Profit after tax |
SEK 28.7m |
SEK 22.2m |
Increased |
Cash flow from operating activities |
SEK 96.3m |
SEK 152.6m |
Lower |
Source: company interim report; percentage-point changes are calculated from reported figures
The results distinguish reported revenue growth from the underlying pace of business expansion. Revenue rose by 3%, but organic growth was just 2%. Management’s report attributes approximately one percentage point of growth to acquired revenue associated with the step acquisition of Viyo, while currency impact was rounded to zero.
Operational earnings also weakened. The 20.5% operational EBITDA margin compared with 21.7% a year earlier, while operational EBIT fell 8% to SEK 122.3 million. Profit after tax, by contrast, rose to SEK 28.7 million from SEK 22.2 million. The divergence underlines why headline net profit alone does not capture the quarter’s softer operating performance.
Reported EBITDA was SEK 152.2 million and included a SEK 2.1 million non-operational adjustment associated with the Viyo step acquisition. The company’s operational EBITDA figure of SEK 150.1 million is therefore the more appropriate measure for the operating comparison above.
What caused the slowdown?
Swedencare’s chief executive, Håkan Lagerberg, identified three principal factors behind the weaker-than-expected organic growth.
1. Manufacturing disruption during an inspection
A September inspection under the Safe Quality Food (SQF) programme affected production more than anticipated. The inspection had a positive outcome, with an additional facility approved, but the operational disruption constrained production during the quarter.
2. Weaker late-quarter performance from European veterinary brands
Despite strong overall organic growth in Europe, some of Swedencare’s European veterinary brands developed more weakly than management expected towards the end of September. This contributed to the group missing its growth expectations.
3. Supply-chain challenges and delayed deliveries
Supply-chain problems delayed customer deliveries and negatively affected online sales for some brands. The timing of these issues was particularly important because the shortfall emerged towards the end of the quarter.
Management said it had expected Q3 organic growth to remain close to the 7% delivered in Q2. The actual 2% outcome was therefore a material disappointment.
Regional and business-segment performance: Europe and production outperform
The group’s headline growth masks a pronounced divide between its operating areas.
Region or business area |
Q3 organic growth |
Business interpretation |
|---|---|---|
Europe |
+11% |
Strong growth, although some veterinary brands weakened late in the quarter |
Production segment |
+11% |
Strong demand, particularly in Europe, the UK and Pharma |
North America |
−4% |
Continued weakness in the US veterinary channel and challenges at NaturVet |
Europe and Production each delivered 11% organic growth, providing important support to group performance. The company also reported strong demand from existing and prospective customers for production capacity in the European Union, the United Kingdom and its Pharma business.
North America remains the principal challenge. The company highlighted continued weakness in the US veterinary channel and ongoing efforts to improve NaturVet’s performance. Management expects a gradual improvement for the brand over the coming years and anticipates that larger partnerships could support performance ahead of launches planned for early 2027.
The contrast has strategic implications. Strong European and contract-manufacturing performance indicates that demand remains healthy in parts of the business, but these areas have not fully offset weaker North American trading and execution problems. The next test is whether the company can translate manufacturing capacity and commercial partnerships into consistent revenue growth.
Product and manufacturing developments
Swedencare reported continued momentum for ProDen PlaqueOff, its pet oral-care product, which grew by more than 30% for another quarter, according to the company commentary reported by Investing.com. This provides a positive counterpoint to the broader slowdown and suggests that selected established products continue to perform well.
The company also highlighted developments in its manufacturing and product portfolio:
-
FDA pre-approval inspection: Swedencare’s Pharma unit passed a US Food and Drug Administration pre-approval inspection for a customer product. Manufacturing is planned to begin in 2027. This is a manufacturing-readiness milestone for a customer product, not an announcement that Swedencare has received approval for a new proprietary drug.
-
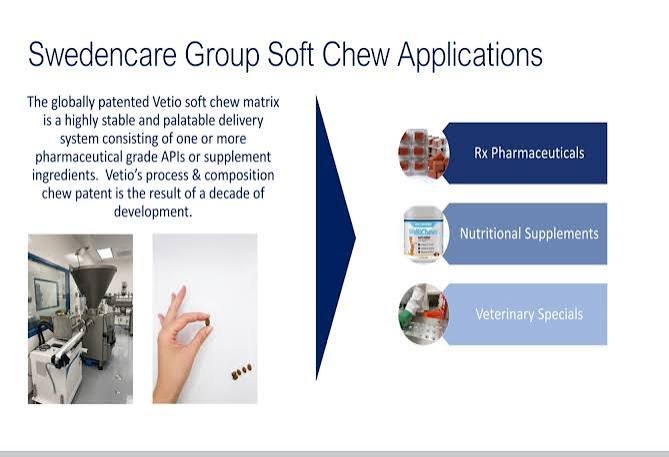
Summit Vet: The subsidiary expanded its product offering to include soft chews following a collaboration with sister company Vetio.
-
NaturVet: Management is working on a turnaround, with larger partnerships and launches planned for early 2027 expected to support future performance.
These developments offer potential routes to growth, but their financial contribution will depend on execution, launch timing, customer demand and the pace at which production and distribution normalise.
Nine-month performance: modest revenue growth, lower operating EBIT
For the first nine months of 2026, Swedencare reported revenue of SEK 2,052.5 million, up 3% from SEK 2,000.8 million in the same period of 2025. Organic, currency-adjusted growth was 6%, compared with 9% a year earlier.
Financial metric |
January–September 2026 |
January–September 2025 |
Year-on-year change |
|---|---|---|---|
Net revenue |
SEK 2,052.5m |
SEK 2,000.8m |
+3% |
Organic, currency-adjusted growth |
6% |
9% |
−3 percentage points |
Operational EBITDA |
SEK 407.2m |
SEK 402.3m |
+1% |
Operational EBITDA margin |
19.8% |
20.1% |
−0.3 percentage points |
Operational EBIT |
SEK 327.8m |
SEK 340.9m |
−4% |
Profit after tax |
SEK 70.1m |
SEK 39.1m |
Increased |
Operating cash flow |
SEK 239.8m |
SEK 282.1m |
Lower |
Source: Swedencare Q3 2026 interim report.
The nine-month figures reinforce the message from the quarter: revenue continues to grow, but underlying growth has moderated and operational EBIT is lower. Operational EBITDA increased slightly, yet the margin declined from 20.1% to 19.8%.
Profit after tax increased to SEK 70.1 million from SEK 39.1 million. That improvement should be considered alongside the decline in operating cash flow, which fell to SEK 239.8 million from SEK 282.1 million. The different movements in profit and cash flow make working-capital discipline and cash conversion important metrics to monitor in subsequent reporting periods.
Full-year outlook: double-digit growth no longer probable
Swedencare now expects organic growth of approximately 6% for full-year 2026, based on performance through the first nine months. Management said double-digit organic growth for the full year was no longer a probable target, although it aims to return to double-digit organic growth in Q4.
The company also announced a planned CEO transition during 2027. Håkan Lagerberg, who has led Swedencare for 12 years, is expected to leave the role no later than the third quarter of 2027. The company said the recruitment process had begun. The transition adds a leadership milestone to a period in which management must also restore confidence in near-term growth execution.

