
Zenrelia and Credelio Quattro lead strong companion-animal performance; adjusted EBITDA increases 23%, gross margin expands 300 basis points and net leverage falls to 2.9x
INDIANAPOLIS, November 6, 2026 — Elanco Animal Health Incorporated (NYSE: ELAN) reported a strong third quarter for 2026, delivering double-digit reported revenue growth, improved profitability and continued momentum across its companion-animal portfolio. The company generated revenue of $1.265 billion, an increase of 11% year-on-year, supported by robust demand for its newer pet-health products, improved pricing and growth in its global ruminant business.
The results prompted Elanco to raise its full-year 2026 revenue, adjusted EBITDA and adjusted earnings-per-share guidance. The company also increased its innovation revenue target to $1.275 billion and achieved a net leverage ratio of 2.9x adjusted EBITDA at the end of September—an important balance-sheet milestone that management said provides greater flexibility for capital allocation.
The quarter’s performance was particularly notable in Pet Health, where revenue increased 14% to $608 million. Strong demand for Zenrelia, Credelio Quattro and AdTab supported volume growth, while pricing contributed to improved revenue quality. International Pet Health grew 17% on an organic constant-currency basis, while US Pet Health increased 13%.
For the animal-health industry, the results provide a useful indication of the commercial potential of differentiated companion-animal medicines, the importance of successful product launches and the growing contribution of innovation-led portfolios to large animal-health businesses.
Q3 2026 financial performance: Growth accompanied by stronger profitability
Elanco reported revenue of $1.265 billion for the quarter ended September 30, 2026, compared with $1.137 billion in the corresponding period of 2025. This represented reported growth of 11% and organic constant-currency growth of 9%.
Profitability improved faster than revenue. Adjusted EBITDA increased 23% to $243 million, while adjusted EBITDA margin expanded from 17.5% to 19.5%. Adjusted earnings per share rose 42% to $0.27.
Key financial indicators
Financial metric |
Q3 2026 |
Q3 2025 |
Year-on-year change |
|---|---|---|---|
Revenue |
$1,265m |
$1,137m |
+11% |
Organic constant-currency revenue growth |
9% |
— |
— |
Gross profit |
$720m |
$607m |
+19% |
Reported gross margin |
56.9% |
— |
+350 bps |
Adjusted gross profit |
$699m |
— |
— |
Adjusted gross margin |
56.1% |
— |
+300 bps |
Reported net income/(loss) |
$18m |
$(34)m |
Turned profitable |
Adjusted net income |
$136m |
— |
+45% |
Adjusted EBITDA |
$243m |
$198m |
+23% |
Adjusted EBITDA margin |
19.5% |
17.5% |
+200 bps |
Reported EPS |
$0.04 |
$(0.07) |
Turned profitable |
Adjusted EPS |
$0.27 |
$0.19 |
+42% |
Source: Elanco Q3 2026 results announcement. Figures in US dollars; margin changes are percentage-point changes.
The difference between reported and adjusted profitability remains important. Reported net income was $18 million, while adjusted net income was $136 million. Investors should therefore consider both measures, alongside the company’s reconciliation of GAAP and non-GAAP results, when assessing underlying earnings performance.
Gross profit increased 19% to $720 million. Reported gross margin reached 56.9%, up 350 basis points, while adjusted gross margin expanded by 300 basis points to 56.1%. Elanco attributed the improvement primarily to higher pricing and a favourable product mix, particularly the performance of US Pet Health and global ruminants.
The company also continued to invest in commercial execution and research and development. Marketing, selling and administrative expenses increased 12% to $393 million, while R&D expenses rose 11% to $99 million. Total operating expenses increased 12% to $492 million.
This combination of margin expansion and continued investment is significant: Elanco is attempting to scale its innovation portfolio while improving operating leverage and cash generation.
Pet Health Emerges as the Principal Growth Engine
Pet Health generated revenue of $608 million, compared with $533 million in Q3 2025, representing 14% growth on both a reported and organic constant-currency basis. The segment benefited from a 9% increase in volume and a 5% increase in price. Elanco attributed volume growth primarily to Zenrelia, Credelio Quattro and AdTab.
The performance of the company’s newer products is especially important because it demonstrates the commercial contribution of its innovation strategy.
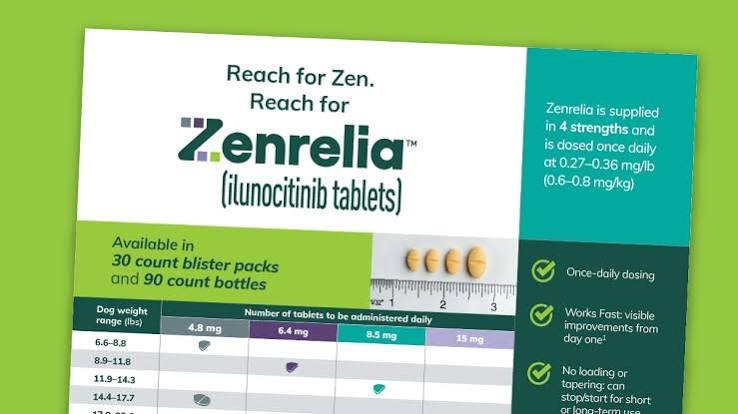
Zenrelia: Record quarterly performance and expanding market share
Zenrelia recorded its largest revenue quarter to date in both the United States and international markets. September was its largest sales month since launch. Elanco reported that US JAK-market share increased by seven percentage points year-on-year, reaching its highest level in September. The company also added approximately 1,600 new US clinics during the quarter, bringing the total to around 19,000.
In Europe, Zenrelia gained 10 percentage points of market share in the first half of 2026, according to the latest available data cited by the company. Elanco estimated that this represented five times the share gain of a competitive entrant.
Commercial significance: Zenrelia’s performance suggests that differentiated dermatology products can gain traction through veterinary-clinic adoption, clinical confidence and continued commercial execution. The addition of new clinics is particularly relevant because it expands the product’s prescribing footprint and potential recurring demand.
Credelio Quattro: Becomes Elanco’s largest US Pet Health branded product
Credelio Quattro continued its strong commercial trajectory, with US market share increasing nine percentage points year-on-year. September was its largest sales month in the quarter and its highest market-share month to date.
The product added approximately 1,600 clinics in Q3, taking total clinic penetration to more than 16,500 clinics, or approximately 55% of the relevant US clinic base cited by Elanco. A particularly important milestone was that Credelio Quattro became Elanco’s largest branded product in US Pet Health, surpassing Seresto in the US market.
The company also announced a positive opinion from the European Medicines Agency for expansion into the European Union, with a launch expected in the first quarter of 2027, ahead of the seasonal demand period.
Commercial significance: The anticipated European launch offers Elanco an additional growth opportunity beyond the US market. The product’s ability to gain clinic adoption and market share will be important to monitor as the company expands its geographical footprint.
Befrena: Expanding access ahead of full launch
Elanco reported that access to Befrena had opened across clinics, including corporate veterinary groups. The company expected all outstanding orders to be fulfilled by the following week and planned to move into a full launch in Q1 2027.
An interesting portfolio observation was that approximately 20% of clinics purchasing Befrena had never previously used Zenrelia. This suggests that a new product can potentially introduce Elanco to additional veterinary customers and create opportunities for broader portfolio engagement. The commercial contribution will depend on the pace of adoption, repeat purchasing and the product’s position within the competitive market.
Established brands continue to contribute
Despite the strong performance of newer innovations, established brands remain important contributors to Elanco’s Pet Health business.
Product family |
Q3 2026 revenue |
|---|---|
Advantage Family |
$115 million |
Seresto Family |
$49 million |
Elanco noted that Seresto was affected by US retailer inventory drawdown, although underlying performance was in line with expectations.
The distinction between retailer inventory movements and underlying end-market demand is important when interpreting quarterly sales of established consumer-facing animal-health products.
Farm Animal: Cattle growth offsets poultry weakness
Farm Animal revenue reached $631 million, compared with $593 million in Q3 2025. This represented reported growth of 6% and organic constant-currency growth of 4%. The segment’s performance was uneven across species, with cattle delivering strong growth, swine recording a modest increase and poultry declining.
Farm Animal revenue by species
Category |
Q3 2026 revenue |
Q3 2025 revenue |
Reported growth |
|---|---|---|---|
Cattle |
$339m |
$289m |
+17% |
Poultry |
$201m |
$217m |
-7% |
Swine |
$91m |
$87m |
+5% |
Farm Animal total |
$631m |
$593m |
+6% |
Cattle was the strongest major species category, with revenue increasing 17% on a reported basis and 11% on an organic constant-currency basis.
Elanco said global ruminants remained its fastest-growing species, with year-to-date revenue increasing 12% on an organic constant-currency basis. Including AHV International and foreign-exchange effects, the increase was 17%.
The company attributed the performance to innovation supporting its beef and dairy portfolios. Poultry revenue declined 7% to $201 million, while swine revenue increased 5% to $91 million. The poultry decline is a notable area to monitor in subsequent quarters. The announcement does not provide enough detail to attribute the decrease to disease incidence, pricing, product mix, market share or customer inventory movements; those explanations should not be assumed without further disclosure.
AHV International adds to the ruminant portfolio
Elanco’s results also reflect the contribution of AHV International, acquired on April 30, 2026. The company noted that AHV contributed to reported growth in Farm Animal and is excluded from the organic constant-currency growth calculation.
The combination of Elanco’s established ruminant portfolio and AHV’s business is strategically relevant to its global cattle and dairy ambitions. The extent to which the acquisition creates incremental growth, cross-selling opportunities and margin improvement will become clearer as integration progresses.
Pricing and product mix support margin expansion
One of the most important features of Elanco’s Q3 performance was the improvement in gross margin. The company reported a 4% increase in price during the quarter, exceeding its expectations. Pet Health pricing increased 5%, with strong sequential acceleration in US Pet Health compared with Q2.
The combination of higher pricing and favourable product mix—particularly stronger sales of US Pet Health innovation and global ruminants—helped lift adjusted gross margin by 300 basis points.
This is an important development for an animal-health company investing heavily in product launches. Newer differentiated products can potentially improve portfolio mix and support pricing, although the sustainability of these benefits depends on competitive intensity, customer acceptance, market access and product lifecycle management.
Elanco also cited early progress from its Elanco Ascend productivity initiatives as a contributor to its improving financial outlook.
Balance-sheet improvement: Net leverage reaches 2.9x
Elanco reported a net leverage ratio of 2.9x adjusted EBITDA as of September 30, 2026, down 0.7x from December 31, 2025. Cash provided by operations was $216 million in Q3 2026, compared with $219 million in the same quarter of 2025.
The achievement of the 2.9x leverage milestone was earlier than management had anticipated.
CFO Bob VanHimbergen said the improvement provides accelerated capital-allocation flexibility. For investors, lower leverage can improve financial resilience and provide greater flexibility to support R&D, commercial launches, debt reduction and other capital-allocation priorities.
The announcement does not specify a new capital-allocation commitment arising from the milestone. The practical impact will depend on management’s subsequent decisions and the company’s cash-generation trajectory.
Elanco raises full-year 2026 financial guidance
Following its Q3 performance, Elanco increased its full-year revenue, adjusted EBITDA and adjusted EPS outlook.
Revised FY2026 guidance
Financial metric |
August 2026 guidance |
November 2026 guidance |
|---|---|---|
Revenue |
$5.090bn–$5.140bn |
$5.155bn–$5.180bn |
Adjusted EBITDA |
$1.010bn–$1.035bn |
$1.050bn–$1.065bn |
Adjusted EPS |
$1.10–$1.16 |
$1.17–$1.20 |
Elanco now expects approximately 8% organic constant-currency revenue growth for the full year, compared with its previous expectation of 6%–7%. The company also raised its innovation revenue target to $1.275 billion.
At the midpoint of the updated range, adjusted EBITDA is expected to increase 17% year-on-year, while adjusted EPS is expected to rise 26%. The company expects adjusted gross margin of 55.8%–56.0%, representing an improvement of approximately 100 basis points compared with 2025.
Elanco said its full-year outlook reflects continued pricing benefits, favourable product mix, savings from the Elanco Ascend initiative and strategic investment in global product launches and the R&D pipeline.
Foreign exchange is expected to provide an approximately $60 million revenue tailwind compared with the previous year. The company cautioned that its organic constant-currency growth calculation excludes foreign-exchange effects, the AHV acquisition and specified royalty revenue and sales-based milestones sold to a third party.
Q4 2026 outlook
Financial metric |
Q4 2026 guidance |
|---|---|
Revenue |
$1.190bn–$1.215bn |
Adjusted EBITDA |
$185m–$200m |
Adjusted EPS |
$0.16–$0.19 |
For Q4, Elanco expects organic revenue growth of approximately 4%–6%, excluding the specified foreign-exchange, acquisition and royalty-related effects. The company anticipates operating expenses increasing approximately 11% year-on-year in constant currency, reflecting continued support for innovation launches and R&D investment.
Early 2027 outlook: Growth algorithm remains intact
Elanco said it expects to build on its anticipated full-year 2026 outperformance and reiterated the annual financial algorithm presented at its December 2025 Investor Day. Its early 2027 expectations are:
-
Revenue: Mid-single-digit organic constant-currency growth.
-
Adjusted EBITDA: High-single-digit growth.
-
Adjusted EPS: Low-double-digit growth.
This outlook signals management’s confidence that the company’s innovation portfolio, pricing momentum, productivity initiatives and commercial investments can support continued growth.
The 2027 outlook is an early expectation rather than detailed formal guidance. Its achievement will depend on the performance of key launches, competitive conditions, currency movements, species-market trends and the company’s ability to sustain margin expansion.
Strategic implications for the global animal-health industry
Elanco’s third-quarter results highlight several developments relevant to animal-health companies, investors, distributors and veterinary businesses.
A. Companion-animal innovation is becoming increasingly important – Pet Health delivered 14% growth, substantially outperforming Farm Animal’s 6% reported growth. The performance of Zenrelia and Credelio Quattro demonstrates the commercial importance of differentiated products supported by veterinary-clinic adoption and sustained launch execution.
The addition of new clinics provides a useful measure of commercial reach, while market-share gains offer an indication of competitive positioning. However, long-term performance will depend on repeat prescriptions, patient retention, product experience and the competitive response.
B. Veterinary-clinic penetration is a critical commercial indicator – Credelio Quattro’s reported penetration of more than 16,500 US clinics, representing approximately 55% of the relevant clinic base, illustrates the importance of distribution and veterinary access.
For animal-health businesses, launch performance is not determined solely by regulatory approval or initial product availability. Converting clinics into active users and sustaining adoption are equally important.
C. Global ruminants offer a significant growth opportunity – The 12% year-to-date organic constant-currency growth reported for global ruminants suggests that the cattle and dairy portfolio is an important contributor to Elanco’s growth strategy.
The contribution of AHV International also makes integration and portfolio development important areas to monitor.
D. Pricing and product mix can support profitability – The 300-basis-point improvement in adjusted gross margin shows how pricing and a favourable product mix can contribute to profitability even as a company continues to invest in launches and R&D.
The sustainability of this improvement will be an important indicator of the quality of Elanco’s earnings growth.
E. Financial flexibility creates strategic options
Reaching 2.9x net leverage earlier than anticipated gives Elanco greater financial flexibility. The company’s future capital-allocation decisions will be relevant to investors assessing the balance between debt reduction, innovation investment, commercial expansion and shareholder returns.
Management commentary and organisational developments
CEO Jeff Simmons described the quarter as evidence of consistent growth, with strong demand for the company’s innovation portfolio and accelerating cash flow. He highlighted the performance of International Pet Health and US Pet Health, the contribution of pricing and volume, and the market-share gains achieved by Zenrelia and Credelio Quattro.
CFO Bob VanHimbergen emphasised the improvement in adjusted gross margin, the impact of pricing and mix, and progress on Elanco Ascend productivity initiatives.
Separately, Elanco announced Jamie Preston as Executive Vice President and Chief People Officer, effective November 3, 2026. Preston joins from Eli Lilly and Company, where she most recently served as Vice President of HR, Global Compensation and Workforce Innovation. She succeeds Dave Kinard, who intends to retire at year-end. The company also reported its highest employee-engagement levels since its IPO and said it had earned Great Place To Work certifications in 11 markets.
What to watch in the coming quarters
Several operating and financial indicators will help determine whether Elanco can sustain its current growth trajectory:
-
Zenrelia adoption: Whether clinic additions and market-share gains translate into sustained revenue growth in the US and international markets.
-
Credelio Quattro’s European launch: The pace of the planned Q1 2027 launch and its ability to establish a meaningful presence in the European market.
-
Befrena’s full commercial launch: Whether the product broadens Elanco’s veterinary customer base and creates additional portfolio opportunities.
-
Poultry recovery: Whether the 7% reported decline in Q3 poultry revenue stabilises or persists.
-
Global ruminant growth: The continued performance of cattle and dairy products and the commercial contribution from AHV International.
-
Gross-margin sustainability: Whether pricing, product mix and productivity savings can maintain the recent margin improvement.
-
Debt and cash generation: Whether the 2.9x leverage milestone translates into sustained financial flexibility and stronger capital allocation.

