HomeCompanion AnimalsU.S. Cat Veterinary Visits Rise 2.7% as Dog Visits Fall 3.3% in...

U.S. Cat Veterinary Visits Rise 2.7% as Dog Visits Fall 3.3% in Q3 2026

CATalyst Council data reveal a widening divergence in companion-animal veterinary demand, with feline visits increasing for 12 consecutive quarters while puppy visits remain substantially below pre-pandemic levels.

UNITED STATES | 14 October 2026 — Veterinary clinical visits for cats in the United States increased 2.7% year over year in the third quarter of 2026, while visits for dogs declined 3.3%, according to Vetsource data cited in the latest Feline Veterinary Market Insights: Volume VII from the CATalyst Council. The figures point to a continuing divergence in veterinary-service demand between the two largest companion-animal segments.

The CATalyst Council reported that feline clinical visits increased in each of the last 12 quarters, whereas canine visits declined in 11 of those quarters. Across all species covered by the reported Vetsource data, clinical visits fell 1.9% year over year in Q3 2026. The findings were announced on 13 October.

The trend is commercially relevant for veterinary practices, diagnostic companies, pharmaceutical manufacturers and pet-care service providers. It suggests that feline care is becoming an increasingly important component of companion-animal practice at a time when the flow of new canine patients is weakening.

Cats account for a growing share of clinic visits

Vetsource data show that cats represented 24% of companion-animal clinical visits in Q3 2026, up from 21% in Q3 2023. The analysis covers wellness and non-wellness visits and is based on 6,595 veterinary practices that reported data in every quarter from Q4 2022 through Q3 2026, with results normalised to Monday-to-Friday business days.

The report also highlights a substantial gap between cat ownership and veterinary attendance. According to the CATalyst Council’s 2026 State of the Cat Report, based on a survey of approximately 60,000 U.S. households, cats account for 46% of household cats and dogs, but only around 33% of household cats visit a traditional veterinary practice annually.
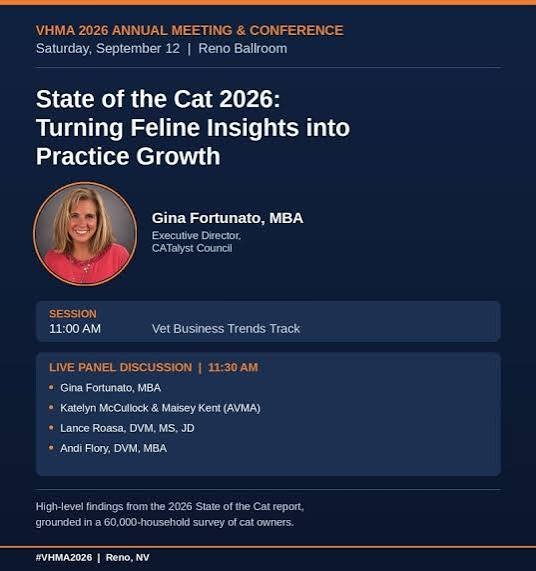
That gap represents a potential opportunity to improve preventive care and strengthen the relationship between veterinary practices and cat owners. However, the available data do not establish why individual cats miss appointments or how much additional clinical demand could be generated by reducing barriers to care.

Kitten and puppy visits reveal different demographic trajectories

The latest figures for July–September 2026 offer an early indication of the direction of kitten and puppy visits in fiscal year 2027, which began in July.

Kitten visits were 0.9% lower than in the corresponding period of 2025. Despite this modest decline, the CATalyst Council estimates that kitten visits could finish the fiscal year approximately 11% above the 2018–2019 pre-COVID baseline. Kitten visits have remained above that baseline in every fiscal year since FY2021; if the current trajectory continues, FY2027 would be the seventh consecutive year above it.

Puppy visits present a more difficult picture. They fell 10.0% year over year during July–September 2026, putting them on course to finish FY2027 around 44% below the pre-COVID baseline, according to the council’s analysis. These are trajectory estimates rather than final full-year results.

The distinction matters because new-patient numbers influence the future composition of the veterinary patient population. Smaller puppy cohorts can mean fewer dogs entering the care system and fewer opportunities for routine visits as those animals age. Subsequent increases in puppy numbers may not fully offset the effect of earlier, smaller cohorts.

The CATalyst Council’s wider demographic analysis has described a scenario in which combined dog and cat clinical visits decline by approximately 1%–2% annually over the next decade. This should be treated as a forecast scenario, not a guaranteed outcome.

Implications for diagnostics, medicines and veterinary practice

The contrast between feline and canine trends has implications across the companion-animal healthcare value chain.

Feline diagnostics and chronic-disease management: More feline visits may create additional opportunities to identify health problems, monitor chronic conditions and improve preventive-care compliance. The data do not, however, show that diagnostic spending or disease prevalence has increased.

Veterinary pharmaceuticals: Manufacturers may wish to examine feline-specific treatment categories, dosing requirements and owner-adherence challenges. Visit growth alone cannot establish demand for any particular drug or therapeutic class.

Clinic operations: Practices could review appointment availability, cat-friendly handling, preventive-care reminders and follow-up systems. Converting early kitten visits into ongoing adult and senior-cat care may be particularly important, given the gap between kitten attendance and annual visits among household cats.

Commercial planning: Suppliers should avoid applying historic, uniform growth assumptions across dogs and cats. Species-specific patient trends may provide a more useful basis for assessing practice demand, although they need to be combined with pricing, treatment mix, patient numbers and spending data.

Jon Ayers, chair of the CATalyst Council’s Data & Market Insights Committee, said the growth in feline care had become strategically important for practices as puppy visits weakened. Executive director Gina Fortunato highlighted the challenge of retaining kittens as lifelong veterinary patients.

What to watch next

The key indicators are whether feline visits continue to grow, whether kitten attendance translates into sustained adult-cat care, and whether puppy visits recover from their current decline. Future reports will also help clarify whether the gap between cats and dogs persists across geographic areas, clinic types and categories of veterinary service.

The Q3 data do not prove that feline veterinary spending, diagnostic revenue or pharmaceutical sales have risen at the same rate as visit numbers. They do, however, establish a meaningful shift in reported clinical activity.

For the veterinary industry, the central message is clear: cats are accounting for a growing share of clinical visits, while declining puppy attendance presents a longer-term challenge for canine patient acquisition.

Animal Health India Editorial Team
Animal Health India Editorial Teamhttps://animalhealthindia.com
Animal Health India (AHI) is an independent news and intelligence platform covering the global animal health, veterinary, livestock, poultry, companion animal and pet food sectors. Our editorial team comprises veterinary journalists, animal health professionals, regulatory affairs specialists and industry analysts with over 30 years of combined experience covering India, Asia, Europe and North America. AHI publishes news, regulatory updates, market intelligence and company news drawn from primary sources including DAHD, EMA, USDA, AVMA and leading veterinary publications worldwide.
RELATED ARTICLES