
Elanco Animal Health has outlined its growth strategy, improving profitability and accelerated balance-sheet deleveraging at the UBS Global Healthcare Conference, reinforcing management’s confidence in the company’s medium-term financial outlook.
During the 9 November conference, Chief Financial Officer Bob VanHimbergen and Bobby Modi, Executive Vice President for US Pet Health and Global Digital Transformation, discussed the company’s operating performance, product innovation, growth opportunities and capital allocation priorities.
The discussion follows Elanco’s third-quarter 2026 financial results, which demonstrated strong organic revenue growth, expanding gross margins and an improvement in its net leverage ratio.
The company’s presentation is particularly relevant to the animal-health industry because it provides insights into the commercial performance of innovative companion-animal medicines and the financial contribution of higher-margin product portfolios.
Third-quarter performance: 9% organic growth and improving profitability
Elanco reported the following third-quarter 2026 results:
Quarterly revenue – $ 1,265 Bn
Reported revenue growth – 11%
Organic constant-currency growth – 9%
Gross margin expansion – 300 basis point expansion
Adjusted EBITDA – $ 243 Mn
Net leverage ratio – 2.9X
The company’s organic constant-currency revenue growth was driven by strong performance across both companion-animal and farm-animal businesses. Pricing contributed approximately 4% to third-quarter growth, while volume increased approximately 5%.
Approximately one percentage point of reported growth came from the Animal Health Vision acquisition completed earlier in 2026. Gross margin expansion was supported by innovative products, manufacturing efficiencies and a more favourable product mix, particularly the contribution from higher-margin pet-health products.
Companion-animal health remains the principal growth engine
The companion-animal segment continues to be a major contributor to Elanco’s commercial momentum. During the third quarter:
Business segment |
Organic constant-currency growth |
|---|---|
US Pet Health |
13% |
International Pet Health |
17% |
The performance reflects growing demand for differentiated veterinary medicines and the company’s ability to expand its market presence.
Management highlighted three important products as contributors to future growth:
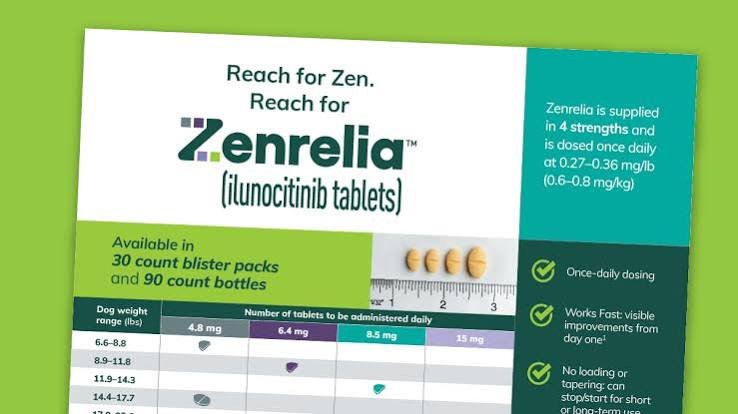
Zenrelia – An oral ilunocitinib treatment for canine allergic and atopic dermatitis. Its commercial performance is important to Elanco’s expansion in veterinary dermatology.


The company indicated that Zenrelia and Credelio Quattro achieved new market-share highs in September 2026. Management also indicated that competitive activity had not fundamentally altered the trajectory of its innovation portfolio.
Farm-animal health: Continuing opportunity for growth
Although companion-animal health is driving much of the recent growth, Elanco continues to view its farm-animal portfolio as an important component of its longer-term strategy. The livestock business provides exposure to several large markets, including:
-
Poultry health.
-
Swine pharmaceuticals.
-
Cattle therapeutics.
-
Ruminant health.
-
Veterinary vaccines.
-
Antiparasitic products.
-
Nutritional and productivity-related solutions.
Elanco’s recent results also highlighted 12% year-to-date organic constant-currency growth in its ruminant business. This is important because it demonstrates that the company’s growth opportunities are not exclusively dependent on companion-animal spending.
Debt reduction: Net leverage falls to 2.9x
One of the most important announcements discussed at the UBS conference was Elanco’s progress in reducing financial leverage. The company’s net leverage ratio declined to 2.9 times adjusted EBITDA.
This represents a meaningful milestone because management had previously expected to reach a leverage ratio below 3.0 times in 2027. Achieving this threshold earlier than anticipated gives the company additional financial flexibility.
Management indicated that the longer-term leverage objective remains approximately 2.0–2.5 times. The company is also discussing the potential implications of its improved balance-sheet position with its board.
This creates the possibility of greater shareholder-return flexibility, although no specific capital-return decision should be inferred from the conference discussion.
Updated 2026 financial guidance
Following the third-quarter results, Elanco increased its full-year financial outlook.
Financial indicator |
Revised 2026 guidance |
|---|---|
Revenue |
$5.155–5.180 billion |
Organic constant-currency growth |
Approximately 8% |
Adjusted EBITDA |
$1.050–1.065 billion |
Adjusted EPS |
$1.17–$1.20 |
Innovation revenue target |
$1.275 billion |
Year-end net leverage target |
Approximately 2.9x |
The company also provided an early 2027 outlook consistent with its previously communicated medium-term financial framework.
2027 indicator |
Management’s expected trajectory |
|---|---|
Organic constant-currency revenue growth |
Mid-single digits |
Adjusted EBITDA growth |
High-single digits |
Adjusted EPS growth |
Low-double digits |
Near-term commercial pressure: Costco OTC distribution
The conference discussion also acknowledged the loss of a Costco brick-and-mortar over-the-counter business. This represents a near-term commercial pressure, particularly in relation to distribution and retail-channel sales.
However, management indicated that the impact would not fundamentally change its deleveraging objectives. The development highlights the importance of distribution-channel diversification in companion-animal pharmaceuticals.
Veterinary clinics, online pharmacies, pet-specialty retailers and mass-market retailers all have different commercial economics. For manufacturers, maintaining strong veterinary recommendation while adapting to changes in retail distribution remains an important strategic challenge.
What Elanco’s performance means for the animal-health industry
Elanco’s results highlight several broader industry trends.
1. Innovation is increasingly driving pharmaceutical growth – Differentiated products can support stronger market-share gains and potentially improve gross margins.
2. Companion-animal medicine remains attractive – Dermatology, parasitology and other chronic or recurring treatment categories provide substantial commercial opportunities.
3. Financial discipline is returning to the strategic agenda – Improving leverage gives pharmaceutical companies greater flexibility to invest in innovation, pursue acquisitions and potentially return capital to shareholders.
4. Livestock health remains an important diversification opportunity – The ruminant business’s growth demonstrates that farm-animal health can provide an additional growth engine.
5. Distribution strategy is becoming more complex – The evolving balance between veterinary clinics, online channels and mass retailers requires manufacturers to rethink commercial execution.
Competitive positioning against Zoetis and MSD Animal Health
Elanco’s improving growth and profitability are relevant in the context of competition with other global animal-health companies.
Competitive dimension |
Elanco |
Industry significance |
|---|---|---|
Companion-animal innovation |
Zenrelia, Credelio Quattro and other products |
Share gains in differentiated therapeutic categories |
Livestock portfolio |
Poultry, swine, cattle and ruminant health |
Exposure to global protein production |
Financial position |
2.9x net leverage |
Improved capital allocation flexibility |
Product innovation |
Raised 2026 innovation target |
Increasing reliance on new product launches |
| Distribution | Veterinary and retail channels | Omnichannel commercial strategy |
The company’s ability to sustain high-single-digit EBITDA growth over the longer term will depend on maintaining product momentum, managing manufacturing costs and continuing to expand its innovation portfolio.
Outlook: Elanco enters 2027 with improved financial flexibility
Elanco’s performance at the UBS Healthcare Conference demonstrates a company with improving operating momentum and a stronger balance sheet.
The combination of 9% organic revenue growth, gross margin expansion and net leverage of 2.9 times provides a stronger foundation for its medium-term strategy. For the animal-health industry, the most important developments to monitor will be:
-
Continued market-share growth for Zenrelia and Credelio Quattro.
-
International pet-health performance.
-
Growth in ruminant and livestock health.
-
Achievement of the revised 2026 guidance.
-
Progress towards the 2.0–2.5x leverage objective.
-
Board decisions concerning future capital allocation.

