

China’s hog-sector controls target secondary fattening and speculative inventory behaviour
CHINA — October 2026: China is continuing efforts to manage imbalances in its hog sector, including measures aimed at reducing speculative production behaviour and discouraging the practice known as secondary fattening, or pig refattening.
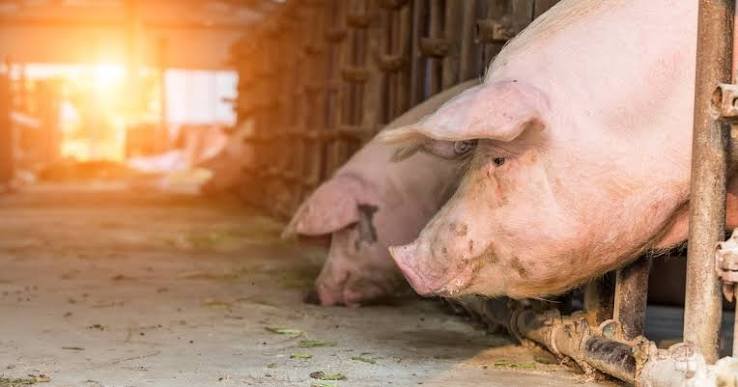
In this practice, traders or smaller operators purchase pigs that are close to normal market weight and keep feeding them for longer, hoping to sell them at a higher weight or when market prices improve. While the strategy can be profitable for individual operators under favourable conditions, widespread participation can alter the timing and volume of animals entering the market.

What is pig refattening?
Conventional pig production follows feeding and finishing schedules designed to bring animals to target market weights. Secondary fattening differs because market-ready or nearly market-ready pigs are retained and fed for additional weeks or months.
The strategy is influenced by expectations about future hog prices, feed costs and the financial return from adding extra weight. It can create challenges when many operators make similar decisions at the same time.
For example, retaining pigs can temporarily reduce the number of animals available for immediate slaughter. If a large number of those pigs are subsequently sold together, the market can experience a concentrated increase in supply.
The result may be greater price volatility, even if the total number of pigs produced has not changed proportionately.
Why is Beijing concerned?
China’s hog sector has faced periods of excess production capacity, weak demand and pressure on farm profitability. Authorities have sought to align production more closely with market demand and limit speculative expansion.
Reuters reported that Chinese authorities were targeting the refattening of market-ready pigs as part of efforts to stabilise prices and improve production efficiency. In May 2026, official Chinese reporting described broader measures to manage hog production capacity, discourage speculative inventory accumulation and support a more stable market.
The policy objectives include:
-
Reducing abrupt changes in the volume of pigs delivered for slaughter.
-
Improving the alignment between production and consumer demand.
-
Discouraging speculative holding of livestock in anticipation of higher prices.
-
Improving feed efficiency and reducing unnecessary production costs.
-
Supporting a more sustainable balance between farm profitability and pork availability.
These goals are interconnected, but the effect of any individual measure will depend on enforcement, farmer behaviour, demand and the overall supply of hogs.
Feed efficiency and environmental implications
Secondary fattening can increase the quantity of feed used per animal. As pigs become heavier, the amount of feed required for each additional unit of weight gain can rise, depending on genetics, diet, health and management.
Where the extra weight does not generate sufficient additional revenue, producers may incur lower margins while using more feed and occupying facilities for longer.
From an industry perspective, reducing inefficient production can potentially improve resource use. However, the outcome should be assessed using actual feed-conversion ratios, average slaughter weights, mortality, farm margins and total pork output—not simply the number of pigs retained for longer periods.
What could the policy mean for hog prices?
The relationship between refattening controls and pork prices is not straightforward.
In the short term, restrictions on holding pigs back could bring more animals to market sooner, potentially increasing immediate slaughter supply and putting pressure on live-hog prices. Over a longer period, measures that reduce excess capacity and discourage speculative production could contribute to a more balanced market.
The outcome will depend on several factors:
Market factor |
Potential effect |
|---|---|
More pigs sold promptly |
May increase near-term market supply |
Lower breeding capacity |
Could reduce future production if sustained |
Weak consumer demand |
May limit price recovery |
Higher feed costs |
Can reduce producer margins |
Stronger pork consumption |
Can absorb supply and support prices |
Uneven enforcement |
May limit the effectiveness of controls |
The policy should therefore not be interpreted as a guarantee that hog prices will rise. Market stabilisation depends on both production decisions and demand conditions.
Implications for global animal-health and feed businesses
China’s hog sector is closely watched by global feed suppliers, genetics companies, veterinary pharmaceutical manufacturers and meat processors. Changes in pig inventories, slaughter weights and production efficiency can influence feed-grain demand, animal-health spending and pork trade flows.
For animal-health businesses, a prolonged period of weak producer margins may encourage farmers to scrutinise input costs more closely. Products that demonstrate measurable improvements in survival, feed conversion, reproductive performance or disease prevention may have a stronger economic proposition, although adoption will still depend on affordability and farm structure.
Feed companies should monitor changes in breeding-sow inventories, slaughter volumes, average carcass weights and feed demand to understand whether policy measures are changing production patterns.
Outlook
China’s refattening controls form part of a broader effort to manage hog production and reduce disruptive supply swings. The effectiveness of these measures will depend on enforcement and whether the industry can adjust production to demand without triggering another period of oversupply or sharp price movement.

