The global sodium butyrate-for-feed market is entering a structurally stronger growth phase as livestock producers adapt to the long-term withdrawal of antibiotic growth promoters (AGPs).
The latest IndexBox analysis, published on 14 September 2026, identifies China’s 2020 withdrawal of growth-promoting medicated feed additives, the European Union’s longstanding AGP prohibition and tighter antimicrobial-use controls in the United States as major demand drivers for sodium butyrate in swine, poultry and aquaculture.
IndexBox’s public release forecasts global sodium-butyrate-for-feed demand at approximately 6–8% CAGR during 2026–2035, with its baseline scenario at about 7.0% CAGR. It also expects protected/coated and microencapsulated forms to capture an estimated 55–65% of market value, reflecting a shift from commodity butyrate toward targeted-delivery products.
The figures cited in the commercial market brief of approximately US$450 million in 2026 rising to US$850 million by 2035 imply a 7.3% CAGR. However, this absolute-value series is not disclosed in the publicly accessible IndexBox article, which instead presents an indexed market outlook. Therefore, the US$450 million/US$850 million figures should be attributed to the underlying IndexBox report rather than presented as independently verified public figures.
Sodium Butyrate Feed Additive Market
1. Why sodium butyrate is becoming strategically important
The significance of sodium butyrate is not simply that it is another feed additive. The industry is undergoing a fundamental transition:
Sodium butyrate is the sodium salt of butyric acid, a short-chain fatty acid. In animal nutrition, butyrate-based products are used principally to support intestinal epithelial integrity, gut environment, microbial balance and feed efficiency.
This makes the category particularly relevant to modern poultry and swine production, where small improvements in feed conversion, mortality, intestinal health and growth can have significant economic value.
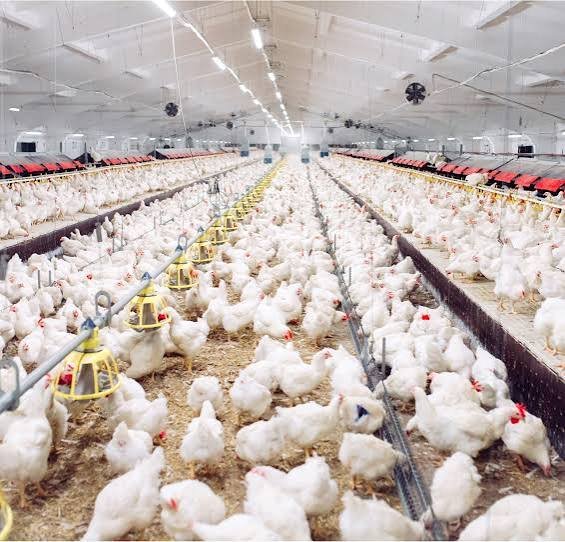
The latest IndexBox analysis identifies swine as the largest end-use sector, while poultry is described as the fastest-growing, particularly in antibiotic-free broiler systems. Aquaculture is another important demand segment.
2. China: the most important structural catalyst
China represents the strongest regulatory catalyst in the global market.
China’s Ministry of Agriculture and Rural Affairs implemented a major change in feed-medication policy beginning 1 January 2020, withdrawing production, import, distribution and use of specified growth-promoting medicated feed additives, with compound-feed production containing those additives ending from 1 July 2020, subject to transition provisions.
This is an important distinction: China’s policy was not simply a ban on “all antibiotics.” Rather, it removed specified growth-promoting drug feed additives, while maintaining separate regulatory pathways for therapeutic/preventive veterinary medicines and certain anticoccidial products.
That distinction matters commercially because it created a large market for non-antibiotic approaches to maintaining intestinal performance. According to IndexBox, Asia-Pacific accounts for an estimated 42% of the sodium-butyrate-for-feed market and is both the largest and fastest-growing regional market. China is identified as a principal driver through its AGP transition, expanding swine and poultry production and aquaculture demand.
China opportunity – The Chinese market therefore has two simultaneous forces:
Demand: large pig + poultry + aquaculture populations
The result is an increasingly sophisticated gut-health market rather than simply an antibiotic-substitution market.
3. European Union: the mature but technically sophisticated market
The EU is further ahead in the regulatory transition. The EU prohibited the use and marketing of antibiotic growth promoters in animal feed from 1 January 2006.
The regulatory framework subsequently strengthened antimicrobial stewardship further, including restrictions on preventive antimicrobial use and antimicrobial use through medicated feed. This means European producers have had considerably longer to develop non-antibiotic gut-health strategies.
IndexBox estimates Europe at approximately 20% of the global sodium-butyrate-for-feed market. It characterises the region as mature, with moderate growth increasingly driven by precision nutrition, premium formulations and specialty products rather than basic volume expansion.
This is where protected and coated sodium butyrate becomes strategically important. Instead of simply supplying sodium butyrate, manufacturers can differentiate through:
microencapsulation;
enteric/targeted release;
protection through feed processing;
controlled intestinal delivery;
combinations with other organic acids;
combinations with probiotics or prebiotics.
IndexBox estimates coated and microencapsulated products could account for 55–65% of market value, illustrating the potential premiumisation of the category.
4. United States: not an outright AGP ban, but a major antimicrobial-use transition
The US requires a more nuanced interpretation. It is not accurate to describe the United States as having a blanket ban on antibiotic growth promoters equivalent to the EU.
Instead, the FDA implemented Guidance for Industry #213 and the Veterinary Feed Directive framework. As of 2017, affected medically important antimicrobial products could no longer be used for production purposes such as growth promotion and required veterinary oversight when used in food-producing animals. FDA states that production indications were withdrawn from all 31 affected applications that included such indications.
This distinction is important for any professional animal-health publication. The commercial consequence, however, is similar in one important respect:
US poultry and swine producers have stronger incentives to maintain performance without relying on medically important antimicrobials for growth promotion.
IndexBox estimates North America at approximately 22% of global sodium-butyrate-for-feed demand, with growth supported by antibiotic-free poultry and swine production and increasing adoption of protected butyrate forms.
5. Does sodium butyrate actually improve animal performance?
The commercial opportunity is supported by an expanding scientific literature, although the evidence should not be overstated.
A 2025 meta-analysis published in Poultry Science evaluated 17 experiments comprising 64 observations and 12,204 broilers receiving protected sodium butyrate. The analysis found improvements in several production and intestinal-morphology parameters. Reported effects included:
Parameter
Effect of protected sodium butyrate
Final body weight
+40 g
Average daily gain
+1.10 g/day
Feed-conversion ratio
−0.015 units
Villus height
+9%
Villus:crypt ratio
+5%
Number of broilers
12,204
Experiments
17
Observations
64
The meta-analysis concluded that protected sodium butyrate moderately improved production performance and intestinal morphology.
These effects may appear modest at the individual-bird level, but in a commercial broiler operation involving hundreds of thousands or millions of birds, even small improvements in FCR, growth rate and gut integrity can have material economic value.
6. Why protected butyrate is more interesting than commodity sodium butyrate
The next stage of the market is unlikely to be driven solely by increasing tonnes of sodium butyrate. The higher-value opportunity lies in delivery technology. Sodium butyrate can encounter limitations related to:
palatability;
stability;
handling;
premature release;
feed-processing conditions;
achieving sufficient activity at the desired intestinal location.
Consequently, protected, coated and microencapsulated formulations become commercially attractive. This explains why IndexBox expects value growth to outpace volume growth and forecasts a substantial share of market value from protected formulations.
The competitive battlefield therefore moves from: “Who can manufacture sodium butyrate most cheaply?”
toward: “Who can deliver the right concentration to the right intestinal site consistently and demonstrate measurable economic outcomes?”
7. Asia-Pacific: the centre of gravity
IndexBox places Asia-Pacific at approximately 42% of the global market, making it both the largest and fastest-growing region. The underlying demand equation is compelling:
IndexBox also identifies local supply expansion alongside continued demand for high-purity and coated imported grades.
That creates an interesting two-tier market:
Commodity segment – Chinese/local manufacturers compete heavily on price and volume.
Premium segment – International and specialist manufacturers compete on:
purity;
coating;
delivery technology;
consistency;
formulation;
field efficacy;
technical support.
8. India: potentially important, but still underpenetrated
India is strategically interesting because it combines a massive poultry industry with relatively strong growth in commercial livestock production and an increasingly sophisticated feed-additive market. The opportunity is particularly relevant to:
broiler gut health;
layer performance;
piglet nutrition;
dairy calf management;
aquaculture;
antibiotic-reduction programmes.
IndexBox lists several India-based companies among its sodium-butyrate competitive landscape, including Palm Nutrients, Kemtron, Agrinova and Biochemicals International.
For India, the major opportunity may not be simply importing European technology. There is scope for India-specific formulations combining butyrate with:
probiotics;
prebiotics;
yeast products;
organic-acid blends;
phytogenics;
enzymes;
toxin binders.
The commercial proposition should be cost per kg of live weight gained or cost per point of FCR improvement, rather than price per kilogram of additive.
9. Market numbers: an important data-quality caveat
The headline figures supplied for this report are:
2026: approximately US$450 million 2035: approximately US$850 million Implied CAGR: approximately 7.3%
Mathematically: US$450m → US$850m over nine years = ~7.3% CAGR.
“The underlying IndexBox market assessment puts the market at approximately US$450 million in 2026 and projects it toward US$850 million by 2035, implying approximately 7.3% CAGR; the publicly available IndexBox release separately describes a 6–8% demand CAGR and a 7.0% baseline.”
10. Strategic outlook: from AGP replacement to precision gut health
The most important conclusion is that sodium butyrate should not be viewed simply as an “AGP replacement.”
Precision gut health → targeted butyrate + microbiome + immune modulation + nutrition
That third generation is where the highest-value opportunity is likely to emerge. For investors and animal-health companies, the most attractive companies will increasingly be those capable of demonstrating:
Gut health / antibiotic reduction / precision nutrition
Bottom line
The sodium-butyrate market is benefiting from a structural—not merely cyclical—change in animal production. China removed specified growth-promoting medicated feed additives from the market beginning in 2020; the EU has prohibited antibiotic growth promoters since 2006; and the US has eliminated production/growth-promotion uses of medically important antimicrobials under its FDA framework.
That regulatory shift is creating persistent demand for technologies that can preserve intestinal integrity, feed efficiency and animal performance without relying on AGPs.
Sodium butyrate is one of the better-positioned technologies in that transition, but the next phase of value creation is likely to come from protected delivery, formulation science, validated field economics and integration with broader microbiome/gut-health programmes, rather than from commodity sodium butyrate alone. IndexBox’s current outlook of roughly 6–8% annual demand growth through 2035 supports that thesis.
Animal Health India (AHI) is an independent news and intelligence
platform covering the global animal health, veterinary, livestock,
poultry, companion animal and pet food sectors. Our editorial team
comprises veterinary journalists, animal health professionals,
regulatory affairs specialists and industry analysts with over 30
years of combined experience covering India, Asia, Europe and North
America. AHI publishes news, regulatory updates, market intelligence
and company news drawn from primary sources including DAHD, EMA,
USDA, AVMA and leading veterinary publications worldwide.