
South Korea | Poultry | Broilers | Production Economics
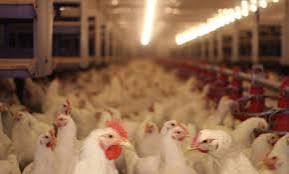
South Korea’s chicken production is forecast to decline by approximately 1% in 2027 to 930,000 metric tonnes, following an estimated increase to 940,000 tonnes in 2026.
The outlook reflects a familiar poultry-cycle dynamic. Highly pathogenic avian influenza during the 2025–26 winter and spring season resulted in the depopulation of approximately 12.2 million chickens, including around 406,000 breeding birds.
Concern about a potential shortage of broiler chicks subsequently prompted integrated poultry companies to expand parent-stock placements. First-half 2026 parent-stock placements reached approximately 3.83 million birds, up around 10.3% year-on-year.
As those birds entered production, domestic chicken availability increased. The resulting supply pressure is now expected to weigh on prices and margins.
The development is important for animal-health companies because poultry profitability directly influences producers’ willingness to invest in preventive health.
The next phase of the Korean poultry cycle is therefore likely to favour technologies that demonstrate measurable improvements in feed conversion, mortality, flock uniformity, breeder performance and disease prevention.
Vaccination, hatchery biosecurity, diagnostics and intestinal-health programmes could remain important, but pricing pressure may increasingly favour products with demonstrable return on investment.
The Korean experience also provides a useful lesson for other poultry markets: aggressive post-disease restocking can rapidly shift a market from shortage to oversupply.
Animal-health industry takeaway
Disease-driven breeding expansion can create a subsequent production surplus. Animal-health companies should expect increasingly ROI-driven purchasing decisions when poultry margins weaken.

